
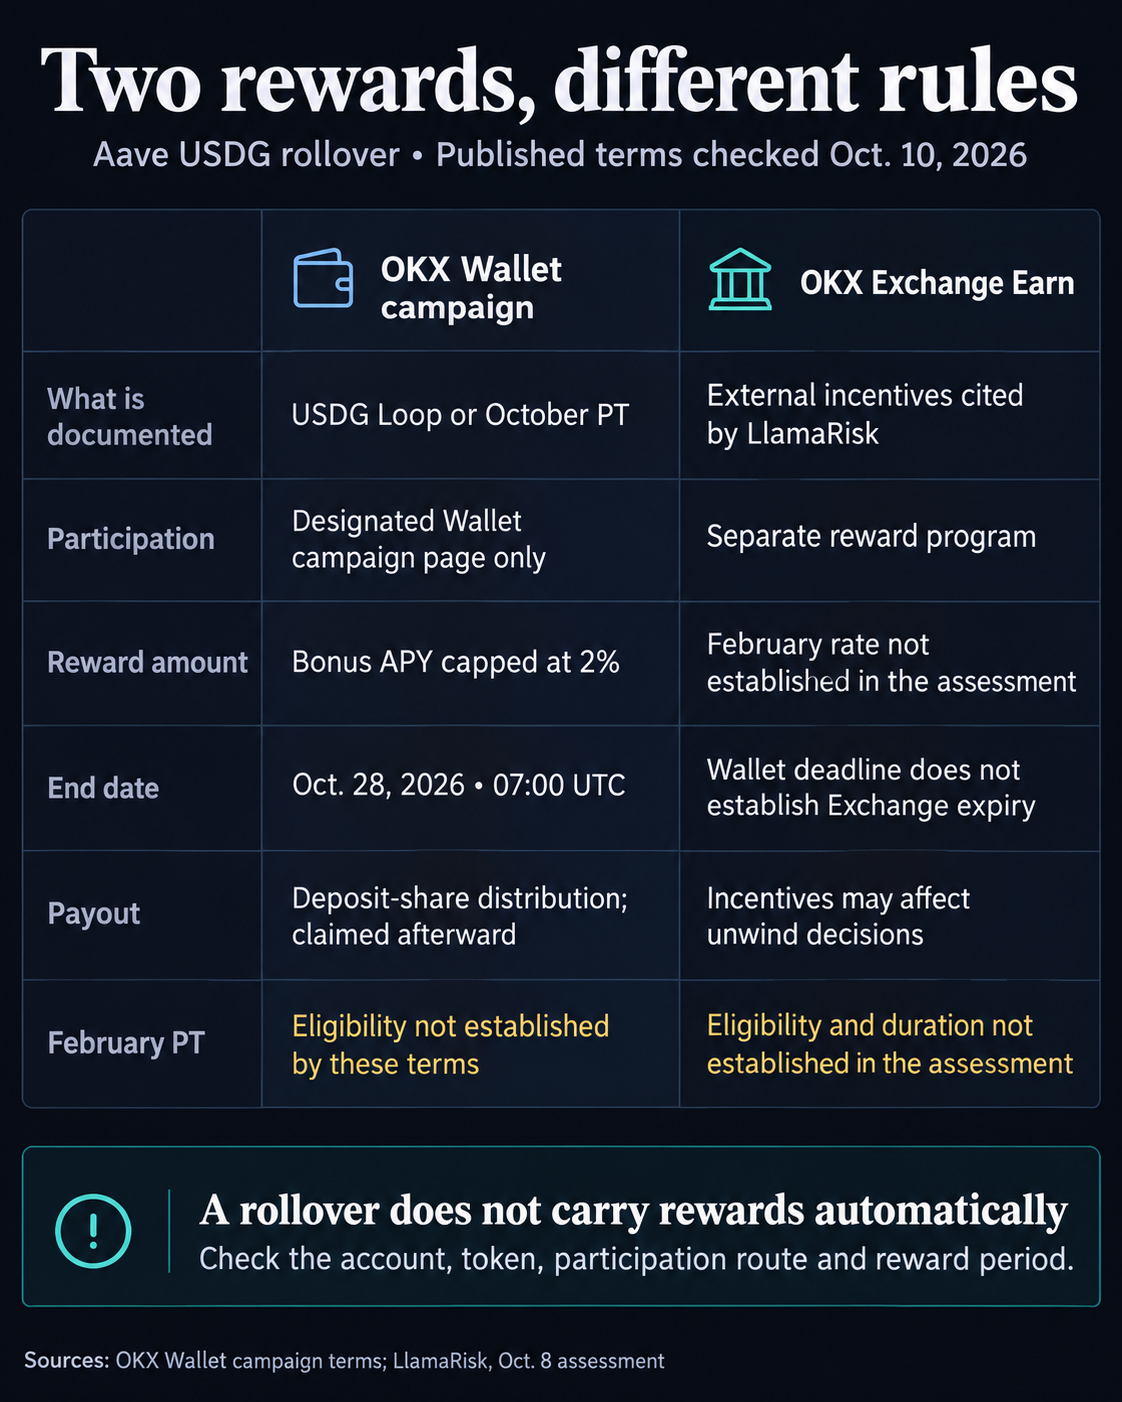
Aave’s proposed USDG rollover would let borrowers carry their stablecoin debt into a new fixed-yield USDG position, but the replacement collateral currently yields less than three quoted borrowing rates. That leaves leverage and separately administered rewards central to whether extending the trade makes financial sense.
Aave’s USDG rollover plan has a yield below most quoted borrowing rates
Aave’s proposed USDG rollover would let borrowers carry their stablecoin debt into a new fixed-yield USDG position, but the replacement collateral currently yields less than three quoted borrowing rates. That leaves leverage and…
CryptoRank
Publisher
Oct 12, 2026 at 3:07 AM UTC · Updated 9時間前 · 6 分で読める
Entities
aave
Last Updated
9時間前
翻訳中…
The proposal concerns Pendle principal tokens, or PTs, on the X Layer network: holders of the token maturing Oct. 29 would move into a replacement maturing Feb. 25, 2027. In its Oct. 8 assessment, risk provider LlamaRisk said the February token’s on-chain yield alone fell short of USDT0, USDC and USDG borrowing costs. GHO was the cheaper exception in that assessment’s Oct. 7 snapshot.
TokenLogic’s proposal would enable a flash-loan transaction that temporarily repays debt, replaces the old PT collateral, borrows again and repays the flash loan. OKX would develop that integration separately. The Aave listing and separate OKX integration would both need to be implemented.
An Oct. 10 refresh preserves the gap. Pendle’s market API reported a February PT implied annual percentage yield of about 2.98%, with data updated at 21:09 UTC. Aave’s X Layer market display, retrieved at 21:11 UTC, showed variable borrowing APYs of 4.12% for USDT0, 5.87% for USDC and 3.75% for USDG.
Article Intelligence
Key Entities
AavePendle
Sponsored
Ad
NewsLayerLearn more
NewsLayer Premium
Unlock deeper intelligence.
Ad-free reading, exclusive research, and real-time onchain insights.
Go Premium