
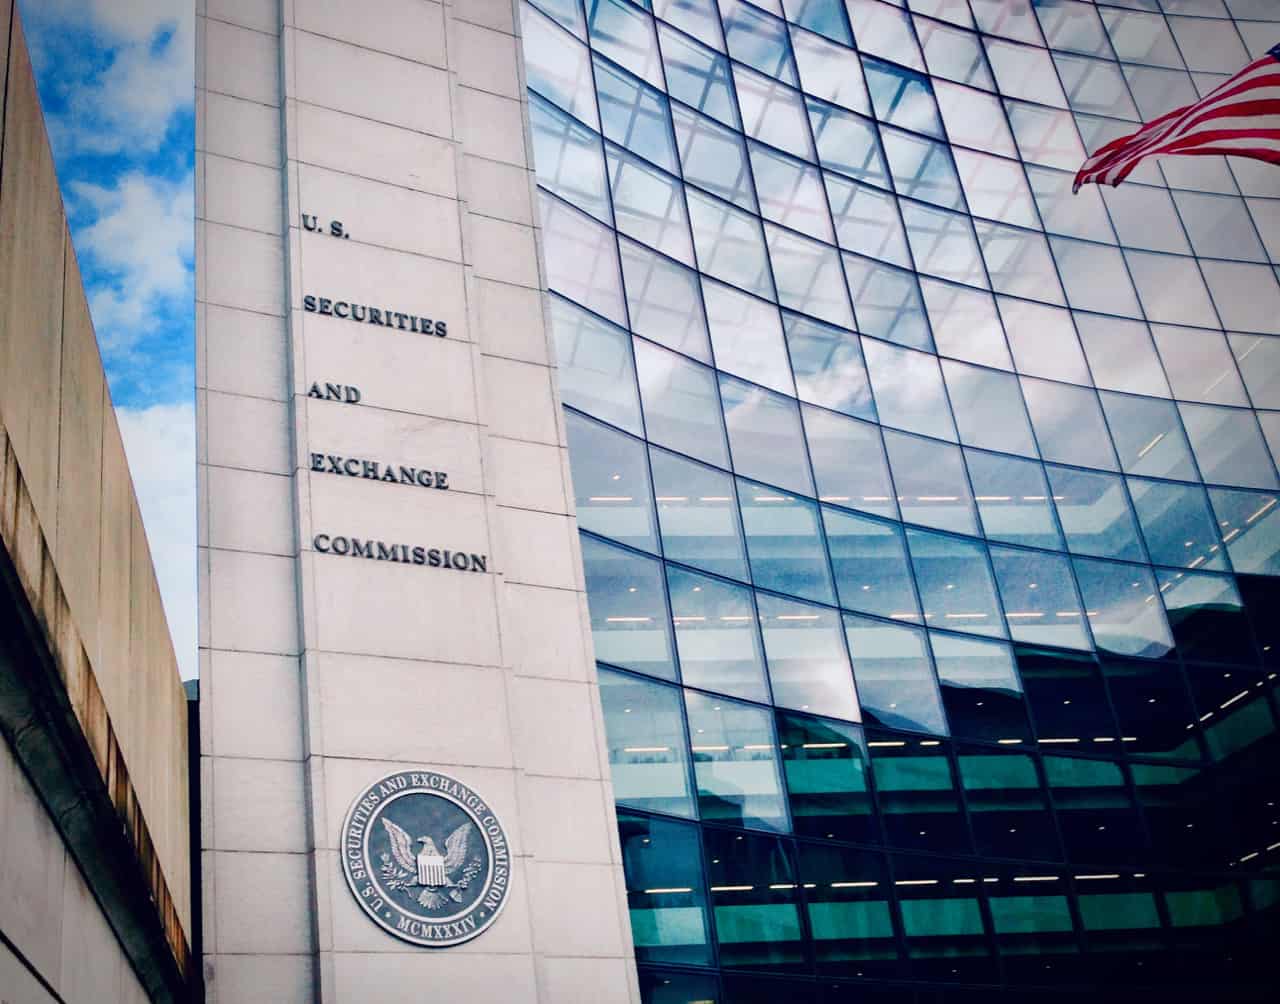
US securities staff have offered a more precise reading of how existing law applies to two common crypto practices: token repurchase programs and tokens issued in liquid staking. In staff-level FAQs released September 25, 2026, the SEC’s Division of Corporation Finance said that, in defined circumstances, those activities do not themselves create an investment contract under the Howey analysis.
SEC Officials State that Certain Crypto Buybacks and Staking Tokens Fall Outside Existing Securities Laws
SEC officials said certain crypto buyback arrangements and staking tokens may fall outside existing securities laws. The statement, reported by Crowdfund Insider, suggests some crypto structures may not be regulated as securities under…
crowdfundinsider.com
Publisher
Sep 28, 2026 at 12:32 AM UTC · 3 min de lecture
Traduction…
The answers are staff views only.
They are not Commission-approved rules and do not change the statute.
The buyback discussion turns on whether a network is already operating.
When a crypto system is functional and the token is not itself a security, announcing a repurchase—for treasury management, supply reduction, protocol burns, or rebalancing—does not amount to a pledge of essential managerial effort.
That kind of pledge is what can convert a token offering into a security.
The picture changes if the network is still unfinished.
In that setting, presenting a buyback as a source of yield or return for holders can look like a promise that profits will depend on the issuer’s work.
Staff applied a similar fact-specific lens to staking receipt tokens.
When a receipt simply evidences ownership of an underlying digital commodity that is not subject to an investment contract, the receipt can be treated as a digital tool.
Article Intelligence
Regulation Signal
in progressUpdated il y a 2 mois
SEC Crypto Asset Market Structure RulemakingRelated Coverage
 MarketsBitcoin ETFs Erase 2026 Losses as Treasury Buybacks Fuel Rallyil y a 2 heures · 3 min read
 PolicyHeads I Win, Tails You Lose? Courts Wrestle With Crypto Price Volatilityil y a 2 heures · 1 min read
 CryptoSaylor Calls for Bitcoin Rights at DC Policy Summitil y a 2 heures · 4 min read
Sponsored
Ad
NewsLayerLearn more
NewsLayer Premium
Unlock deeper intelligence.
Ad-free reading, exclusive research, and real-time onchain insights.
Go Premium